What Your Insurance Won't Cover After a Basement Flood
Sewer backup, gradual seepage and the maintenance exclusion. These are the three refusals Mississauga homeowners run into every spring.
By WDR Mississauga 6 min read
Almost every Mississauga homeowner we meet believes the basement is covered. Most are partly right, and the part they have wrong is usually the part that just flooded. Ontario water coverage is built from separate pieces, and which piece matters depends entirely on where the water came from.
1. Sewer backup is a separate endorsement
A standard Ontario homeowner policy does not cover sewer backup. It covers sudden and accidental water escaping from plumbing inside your home, which is the burst pipe case. Water rising back up through a floor drain, a toilet or a laundry standpipe is different. That needs a sewer backup endorsement. You buy it on its own and it carries its own deductible.
Say your basement took water in a summer storm and it came up through the floor drain. Your adjuster asks about that endorsement first. Check your declaration page now, rather than in March. This rider is one of the cheapest on the policy and the most likely claim in this city.
2. Overland water is a third, different endorsement
Sewer backup and overland water are two separate products on a home insurance policy, and they never come bundled. Overland flood coverage responds to surface water entering at grade. Think of a swollen Cooksville Creek, or runoff pouring down a driveway into a window well. Many Canadian insurers only started selling it after 2015. Plenty of older policies still carry none of it.
Sudden and accidental is covered. Gradual and foreseeable is not. Nearly every declined claim we see turns on which side of that line the adjuster lands.
3. The maintenance exclusion
Every Ontario policy excludes damage from wear, deterioration and lack of maintenance. There are 5 situations where that exclusion decides the outcome:
- A supply line that burst at 2am is sudden. Covered.
- A shower pan weeping into the joists for two years is gradual. Not covered.
- A sump pump that failed during a storm may be covered, if you carry the sump failure rider.
- A sump pump that failed with a seized float and no service history is maintenance. Argued, often declined.
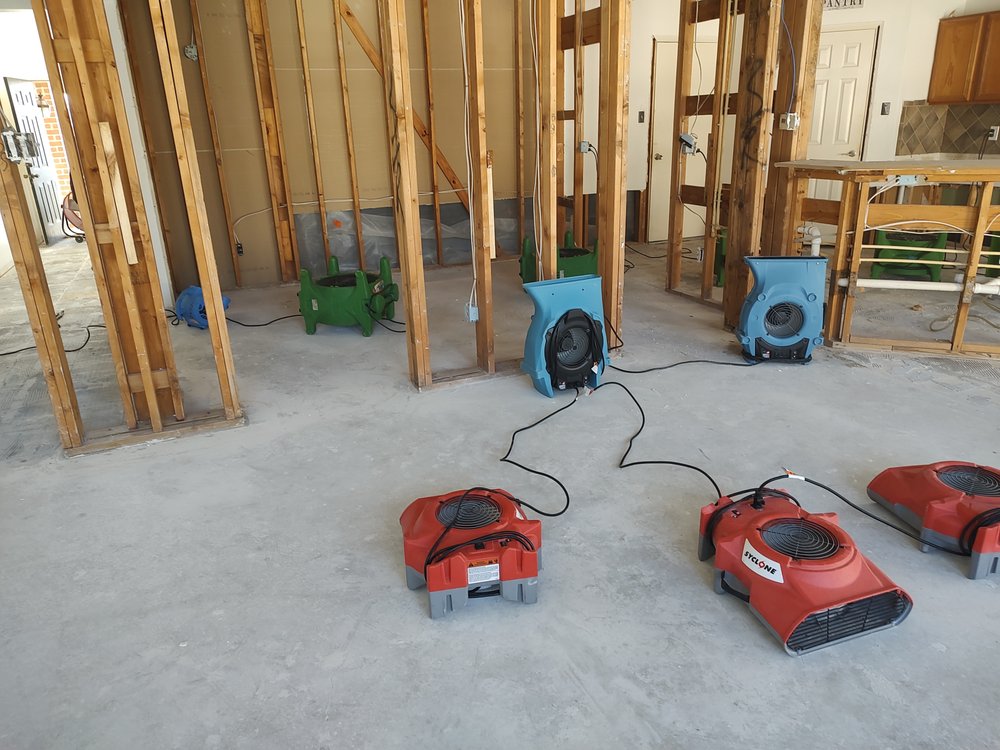
- Foundation cracks letting in seepage every spring are excluded outright, even where the basement flood cleanup bill is large.
Documentation earns its keep right here, which is why our insurance claim support starts on day one. A dated moisture log helps. So do photographs taken on the day of the loss. Together they make it far harder for anyone to recast a sudden event as a long-running one.
4. What is usually covered, and how far
Where a loss qualifies, most Ontario policies pay for 4 things. Extraction. Structural drying. Removal and replacement of damaged building materials. Additional living expenses, where the home cannot be lived in. Contents are covered to your policy limits. That is often actual cash value rather than replacement cost, unless you paid to upgrade.
Upgrades are the part they will not pay for. Rebuild a 1978 panelled basement in drywall with pot lights and the difference falls to you. That is indemnity working as designed, putting you back where you were rather than somewhere better.
5. The deductible you did not know you had
Water endorsements frequently carry their own deductible, separate from and higher than your main policy deductible. A $1,000 policy deductible can sit beside a $2,500 sewer backup deductible. On a $6,000 basement claim, that changes the arithmetic a long way.
Condo owners carry one more layer. Section 105 of the Condominium Act, 1998 lets the corporation charge its deductible back to you, if the damage started inside your suite. Those chargebacks run $10,000 to $50,000 routinely, and condo restoration scoping is what keeps them defensible. Deductible assessment coverage on a unit owner policy exists for exactly this.
Is sump pump failure covered in Ontario?
Only if your policy has sump pump failure coverage, and only if the pump failed suddenly. On many Ontario policies, sump failure sits inside the sewer backup endorsement. On others it is a separate line, and on older policies it is missing entirely. Read the wording, not the summary. Some policies cover water that enters because the pump failed. Others cover only water that comes back up through the pit.
The adjuster will ask three things. Did the pump stop because of a power cut, a mechanical failure or a blocked discharge? Was it serviced? Was the pit sized for the water it had to move? A pump that burned out in a storm with a service record behind it is a strong claim. A pump with a float that seized years ago reads as maintenance, and that falls under the exclusion above. Keep the failed pump. It is evidence, and our basement flood cleanup crew photographs it in place before it comes out.
Sewer backup endorsement limits
A sewer backup endorsement does not always pay up to your full home coverage. Many carry their own limit, and $10,000, $25,000 and $50,000 caps are all common. A finished basement in Mississauga can run past the lower figures once sewage cleanup, contents and the rebuild are added together.
Check 3 numbers on the endorsement: the limit, the deductible, and whether contents share the same limit as the building. Some insurers also lower the limit or raise the deductible after a first claim, or require a backwater valve before they renew. If your basement is finished, ask your broker what it costs to move the limit up one step. It is usually a small change to the premium next to the gap it closes.
Overland water after the 2024 storms
Mississauga had two storms in the summer of 2024 that the City described as historic. More than 106 mm fell on July 16. Up to 170 mm fell on parts of the city on August 17. Creeks across the city spilled into parks, and Pearson recorded its wettest summer on record. Many of the claims that followed turned on one question: did the water come up through a drain, or in from the ground outside?
Water that came in at a window well, a door or over the yard is overland water. Without the overland endorsement, it is not covered, even on a policy that has sewer backup. Owners who had only one of the two often found that out in August. If your home sits near Cooksville Creek, Little Etobicoke Creek or any low ground, carry both. Some insurers now price overland coverage by address, so ask for a quote rather than assume it is unavailable.
What to do before you need any of this
Pull your declaration page and find 3 lines: sewer backup, overland water, and sump pump failure. Ask your broker what each missing one costs to add. Then work through the basement flood prevention checklist, since some insurers ask what you have done to lower the risk. Then photograph the finished basement while it is dry, covering the room, the flooring, the cabinetry and the contents. Proving what you had is the other half of a claim, and almost nobody does it in advance.
If your claim is already open, a Mississauga restoration company that documents from day one makes the adjuster conversation shorter. Our insurance claim support sends the scope, the photos and the moisture logs straight to your insurer.
Published July 28, 2026 by WDR Mississauga. Rebates, bylaws and insurance terms change, so confirm details with the program, your corporation or your insurer before you act.